The US beverage producer says its three-year funding programme is starting to ship, with new RTD and single-serve capability supporting income development, narrowing losses and a stronger pipeline of brand name companions
Westrock Espresso has moved into the subsequent section of its development plan, reporting its fifth consecutive quarter of year-on-year enchancment in adjusted EBITDA and producing constructive free money stream sooner than anticipated.
The Arkansas-based espresso roaster, packager and provider posted second-quarter web gross sales of $305.7m, up 8.8% from the identical interval final yr. Its web loss narrowed to $13.7m from $21.6m in comparison with a yr in the past, whereas its working loss fell to $1.4m from $15m.
Adjusted EBITDA, Westrock’s most well-liked measure of underlying profitability, rose 38.9% to $21.3m.
Chief Monetary Officer Chris Pledger stated the figures confirmed “continued momentum throughout our platform”. He added that Beverage Options gross sales rose 16.8% to $243.9m, with adjusted EBITDA up 12.7% to $22.2m.
Gross revenue fell 8.8% to $37.7m, nonetheless, as depreciation from the Conway property and non-cash changes weighed on the quarter.
The quarter additionally marked a big milestone for an organization that has spent the final three years constructing out its manufacturing base.
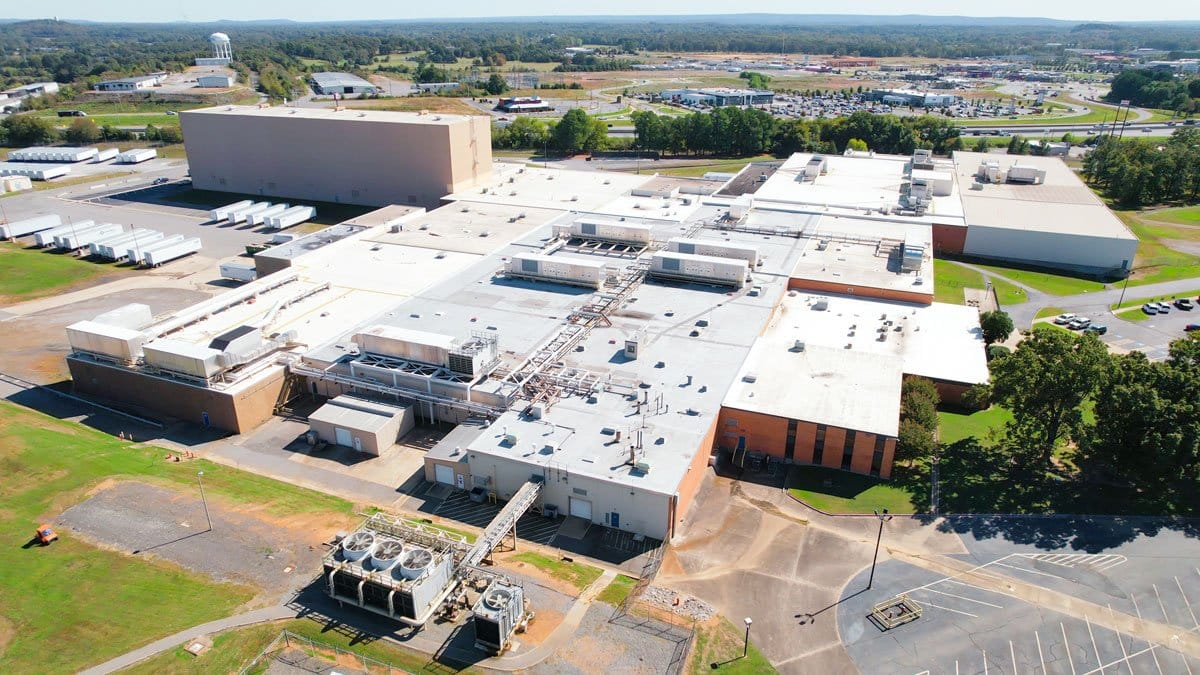
Westrock invested roughly $360m in new RTD and single-serve services, together with its 524,000-square-foot Conway, Arkansas website, which it describes because the world’s largest roast-to-RTD manufacturing facility.
“The platform we spent the final three years constructing now not requires capital. Relatively, it’s a generator of money,” stated CEO and co-founder Scott Ford. Westrock generated $20.2m in free money stream throughout the quarter and was cash-flow constructive for the primary half of the yr, one quarter forward of its earlier schedule.
Conway is now contributing throughout a number of beverage channels. Ford stated Beverage Options development was led by increased volumes of RTD cans, glass bottles and multi-serve codecs, with demand coming from each current and new model companions.
The corporate can also be supplying packaged espresso and single-serve cups, whereas increasing into adjoining classes.
Pledger stated development was supported by “new buyer wins in our flavours, extracts, and components enterprise, together with the launch of a lemonade refreshers program”. Ford stated the pipeline now consists of refreshers, power and high-protein drinks, in addition to purposeful and nutraceutical single-serve cups.
Single-serve espresso volumes elevated 9% year-on-year when excluding a buyer misplaced by trade consolidation. Ford stated Westrock is rising at roughly 4 occasions the speed of the general single-serve cup market, with alternative volumes from new prospects anticipated to start arriving late this yr and construct by 2027.
The corporate says its expanded capability helps it win enterprise throughout a number of product strains. “We’re throughout the board profitable share in each single class that we play in,” Ford instructed buyers. He stated prospects are initially approaching Westrock for one product, then increasing their relationship after seeing the corporate’s manufacturing, sourcing and risk-management capabilities.
Notably, in July Westrock Espresso struck a serious ready-to-drink partnership with Italian espresso illycaffè for the US market.
Westrock expects additional development with out one other main development mission. Ford stated latest can-format wins ought to make Conway an more and more necessary contributor to profitability by the remainder of 2026 and into subsequent yr. The corporate can also be growing 4 new format strains this yr and has eight merchandise in growth that it expects to launch over the subsequent 24 months, supplied they’re supported by dedicated buyer demand.
With its heavy funding section largely full, Westrock reaffirmed its 2026 adjusted EBITDA outlook of $90m to $100m. Pledger stated the corporate’s priorities at the moment are to promote remaining capability, handle its buyer combine and enhance operations throughout its crops.
Ford stated the enterprise is “on the precipice of turning into a really, very totally different enterprise than the one which we have now been”.
The following check might be turning the Conway platform’s rising gross sales pipeline into sustained revenue development, whereas utilizing money technology to cut back debt reasonably than start one other pricey growth cycle.